50/30/20 Budget Rule: Does It Still Work in 2026?
The 50/30/20 budget rule is popular for one simple reason:
It makes budgeting easy to understand.
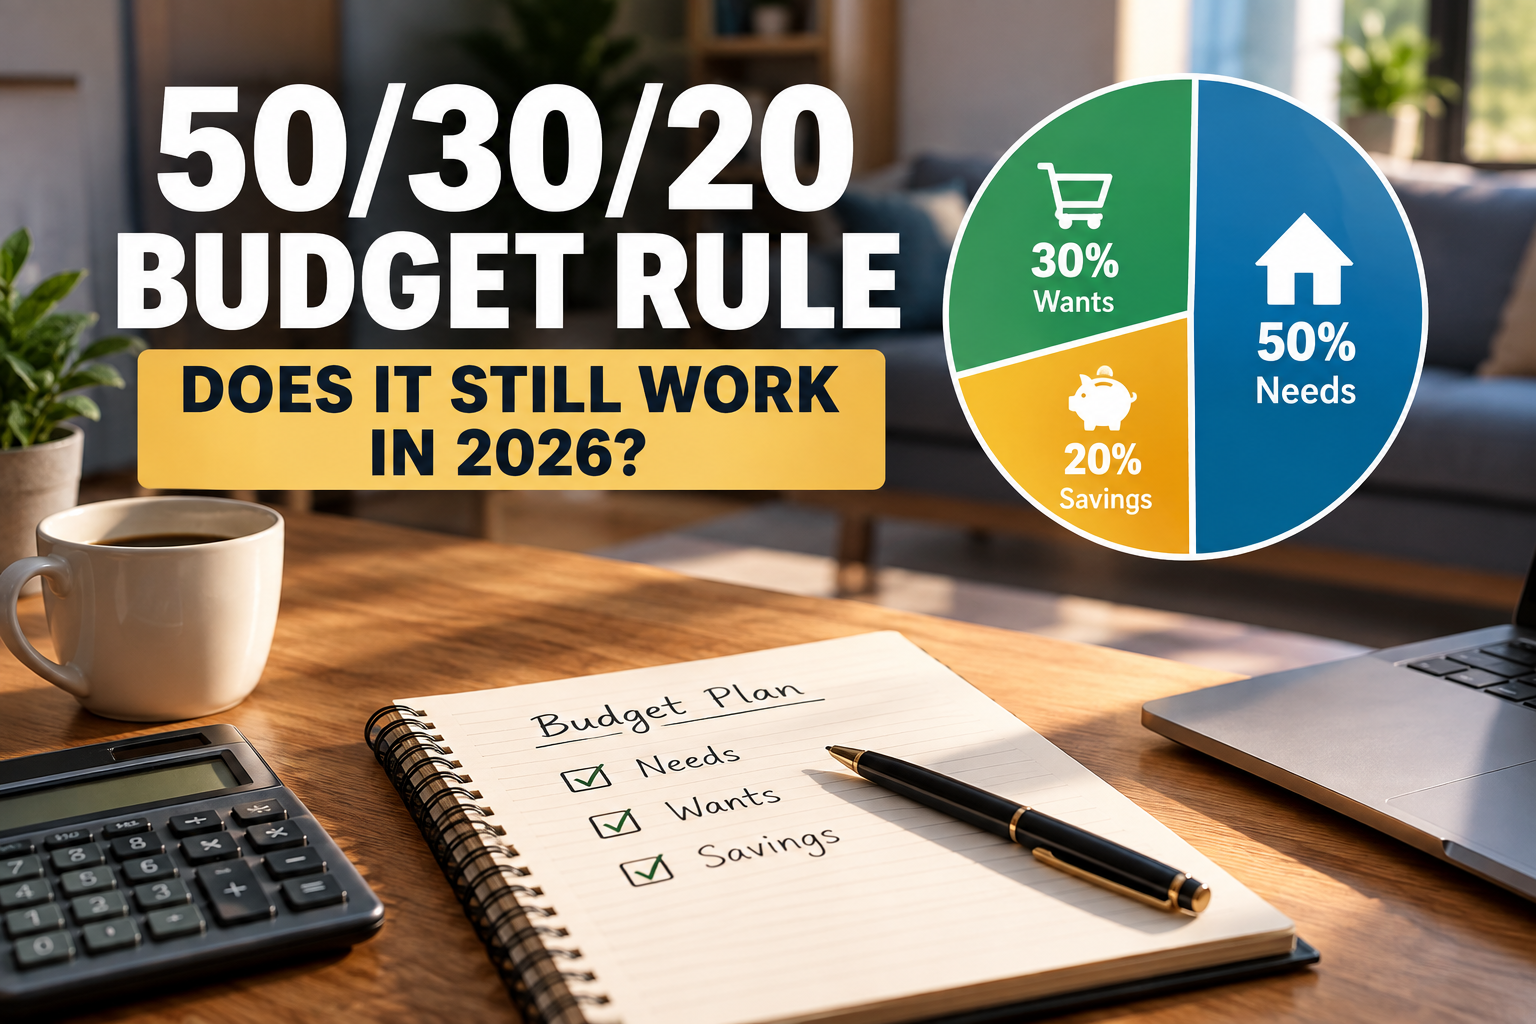
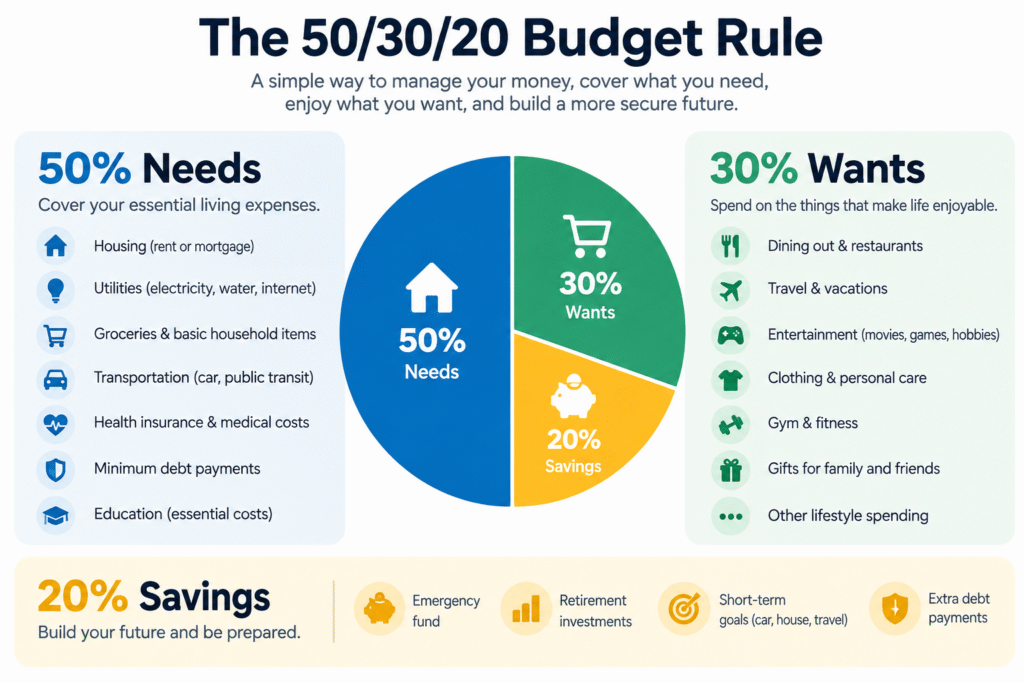
Instead of tracking dozens of categories, you divide your take-home pay into three broad groups:
- 50% for needs
- 30% for wants
- 20% for savings and debt repayment
It is simple, memorable, and useful for beginners.
But does the 50/30/20 rule still work in 2026?
Yes — but it works better as a starting framework than as a strict rule.
For some households, spending only 50% of take-home pay on necessities is realistic.
For others, housing, childcare, insurance, transportation, food, and debt payments already consume more than half of monthly income.
That does not automatically mean the household is budgeting badly.
It means the percentages need to reflect reality.
The Consumer Financial Protection Bureau teaches the 50/30/20 framework using monthly net income, while also noting that not everyone can follow the exact percentages and that people may need their own personal spending rules. Consumer Financial Protection Bureau
This guide explains how the rule works, why it may be harder to follow in 2026, and how to build a version that actually fits your finances.
What Is the 50/30/20 Budget Rule?
The traditional 50/30/20 budget divides your monthly take-home income into three categories:
50% — Needs
30% — Wants
20% — Savings and debt repayment
Suppose your monthly take-home pay is $5,000.
A traditional 50/30/20 budget would look like this:
| Category | Percentage | Monthly Amount |
|---|---|---|
| Needs | 50% | $2,500 |
| Wants | 30% | $1,500 |
| Savings and debt repayment | 20% | $1,000 |
That gives you a simple spending framework without requiring you to plan every dollar individually.
Should You Use Gross Income or Take-Home Pay?
For the 50/30/20 rule, it is generally more useful to work from net income — the money you actually bring home after taxes and payroll deductions.
The CFPB’s budgeting materials specifically describe the framework using monthly net income. Tüketici Finansmanı Dosyaları
However, there is one important detail.
If money is already being deducted from your paycheck for things such as retirement contributions, health insurance, or other benefits, be consistent.
You do not want to accidentally count the same money twice.
For example, if you contribute to a 401(k) before your paycheck reaches your bank account, part of your saving is already happening before you calculate your monthly budget.
What Counts as a Need?
Needs are expenses you realistically need to maintain your basic life and meet financial obligations.
Common examples include:
- Rent or mortgage
- Basic groceries
- Utilities
- Transportation
- Health insurance
- Necessary medications
- Minimum debt payments
- Childcare required for work
- Basic phone service
- Essential internet service
The key question is:
Would I still need to pay for this if I were trying to reduce spending significantly?
That can help separate necessities from lifestyle choices.
For example, transportation may be a need.
But the difference between an affordable used car and a luxury vehicle may partly belong in the wants category.
What Counts as a Want?
Wants are expenses that improve your lifestyle but are not essential to basic living.
Examples include:
- Restaurant meals
- Food delivery
- Vacations
- Entertainment
- Streaming subscriptions
- Nonessential shopping
- Premium electronics
- Expensive hobbies
- Luxury services
That does not mean wants are bad.
A sustainable budget should leave room to enjoy your money.
The goal is simply to know how much of your income is going toward optional spending.
What Counts Toward the 20%?
The final category is usually the money that improves your future financial position.
That can include:
- Emergency fund contributions
- Retirement saving
- Investing
- Extra debt repayment
- Saving for a home
- Other long-term goals
The CFPB’s 50/30/20 materials include savings goals and debt repayment in this category. Tüketici Finansmanı Dosyaları
If you currently have little or no emergency savings, building a cash reserve may be one of the first places to direct this money.
You can link here to:
Emergency Fund: How Much Do You Really Need?
Why the 50/30/20 Rule Can Be Harder in 202The percentages themselves have not changed.
The challenge is whether household expenses fit comfortably inside them.
According to the Federal Reserve‘s 2025 household survey, 58% of U.S. adults said that changes in the prices they paid compared with the previous year had made their financial situation worse. Federal Reserve
Inflation also remains relevant in 2026. The U.S. Bureau of Labor Statistics reported that the Consumer Price Index was 3.4% higher in August 2026 than a year earlier. Bureau of Labor Statistics
This matters because the 50% needs category has to absorb expenses such as housing, food, transportation, utilities, and insurance.
If those expenses rise faster than your income, staying below 50% becomes harder even if your spending habits have not changed much.
The Biggest Weakness of the Rule
The biggest weakness is that it assumes many households can keep total necessities close to 50% of take-home pay.
That may not be realistic.
Consider someone bringing home $4,000 per month.
The traditional rule allows:
$2,000 for needs
Now suppose their essential expenses are:
- Rent: $1,600
- Groceries: $450
- Transportation: $350
- Utilities: $200
- Insurance: $250
Total:
$2,850 per month
That equals:
71.25% of take-home pay
The person has already exceeded the traditional needs target before spending anything on entertainment or saving.
Telling them to “just follow 50/30/20” is not particularly useful.
The better question is:
Which expenses can realistically change, and what savings rate is sustainable right now?
Use 50/30/20 as a Diagnostic Tool
One of the best ways to use the rule is not as a command, but as a comparison.
Instead of treating the 50/30/20 budget rule as a strict financial requirement, use it as a simple benchmark to compare your actual spending habits, understand where your money is going, and identify which parts of your budget may need adjustment.
Calculate your real percentages.
Then ask:
- Are my essential expenses unusually high?
- Am I spending more on wants than I expected?
- Am I consistently saving something?
- Is debt preventing me from saving?
- Is there one large expense driving the problem?
For example, maybe your actual budget is:
58% needs
27% wants
15% savings
You now have useful information.
You can decide whether reducing wants, lowering a major expense, or gradually increasing savings makes sense.
You do not need to force your numbers into 50/30/20 immediately.
Example 1: $3,000 Monthly Take-Home Pay
With $3,000 of take-home income, the traditional framework would be:
Needs: $1,500
Wants: $900
Savings: $600
This can be difficult in many areas if rent alone approaches or exceeds $1,500.
A more realistic temporary budget might be:
65% needs = $1,950
20% wants = $600
15% savings = $450
That is not traditional 50/30/20.
But the person is still saving $450 per month.
That is meaningful progress.
Example 2: $5,000 Monthly Take-Home Pay
Traditional allocation:
Needs: $2,500
Wants: $1,500
Savings: $1,000
Suppose the actual budget is:
Needs: $2,750
Wants: $1,250
Savings: $1,000
The real ratio becomes:
55/25/20
There is nothing inherently wrong with this.
The household is still saving 20% while keeping spending under control.
Example 3: $8,000 Monthly Take-Home Pay
Traditional allocation:
Needs: $4,000
Wants: $2,400
Savings: $1,600
But someone with relatively low fixed expenses may not need to spend 30% on wants.
They might instead use:
40% needs = $3,200
20% wants = $1,600
40% savings = $3,200
The 20% savings category is not a maximum.
If you can comfortably save more, the rule should not stop you.
When 60/20/20 May Work Better
A 60/20/20 budget can be useful when necessities are somewhat higher than the traditional framework allows.
For example:
60% needs
20% wants
20% savings
On $5,000 of monthly take-home pay:
Needs: $3,000
Wants: $1,000
Savings: $1,000
This keeps the same 20% savings target while reducing discretionary spending.
It can be a practical adjustment for someone dealing with higher rent, transportation, or insurance costs.
When 70/20/10 May Be More Realistic
Someone with a lower income or unusually high necessary expenses might temporarily operate closer to:
70% needs
20% wants
10% savings
That is not necessarily an ideal long-term target.
But saving 10% consistently can be much more realistic than trying to save 20% and failing every month.
As income rises or fixed expenses fall, the savings percentage can be increased gradually.
What If You Can Only Save 5%?
Start with 5%.
A realistic savings rate that you can maintain is more useful than an unrealistic target you repeatedly abandon.
Suppose you earn $4,000 per month after taxes.
Saving 5% equals:
$200 per month
Over one year, that becomes:
$2,400, before interest.
Later, you could increase the rate to 7%, then 10%, then higher.
Financial progress does not need to happen all at once.
Link naturally here to:
How Much Should You Save Each Month? A Realistic Guide
What If Your Needs Are Above 60%?
This is where a budget becomes more than a spreadsheet exercise.
First, identify what is driving the number.
Look at your largest expenses:
- Housing
- Transportation
- Debt
- Childcare
- Insurance
- Food
A $15 subscription may be easy to cancel, but it will not fix a budget where housing costs are $800 too high.
Focus on large structural expenses first.
Possible long-term changes might include:
- Moving when your lease ends
- Getting a roommate
- Refinancing or replacing an expensive vehicle
- Shopping insurance rates
- Paying down expensive debt
- Changing childcare arrangements
- Increasing income
Not all of these options will be realistic for every person.
The purpose is to identify the biggest pressure points.
High-Cost City Example
Imagine someone earning $6,000 per month after taxes in an expensive city.
Their monthly needs may be:
Housing: $2,600
Transportation: $500
Food: $600
Utilities: $250
Insurance: $350
Minimum debt payments: $200
Total:
$4,500
That is already 75% of income.
A traditional 50/30/20 budget would not reflect their current reality.
Their first priority may be controlling discretionary spending and maintaining at least some saving while looking for ways to reduce a major fixed expense over time.
Family With Childcare Example
Suppose a household brings home $8,000 per month.
Essential costs include:
Housing: $2,300
Childcare: $1,600
Groceries: $800
Transportation: $700
Utilities and insurance: $700
Total needs:
$6,100
That is more than 76% of take-home income.
The household might temporarily have very little room for wants.
Again, the percentage does not prove they are financially irresponsible.
It shows that childcare and housing are placing significant pressure on the budget.
Freelancer Example
Someone with irregular income faces a different challenge.
One month they may bring home $7,000.
The next month it may be $3,500.
Instead of building their lifestyle around the best month, they might create a baseline budget using a conservative income level.
For example:
Average low-month income: $4,000
Build normal spending around that figure.
When higher-income months occur, extra money can be directed toward:
- Emergency savings
- Taxes
- Retirement
- Investing
- Future business expenses
- Debt repayment
This can make income volatility easier to manage.
Should Minimum Debt Payments Count as Needs?
Usually, yes.
Minimum required payments are obligations.
If you do not make them, there can be serious financial consequences.
Extra debt payments, however, can reasonably be placed in the 20% savings/debt category.
Example:
Minimum credit card payment: need
Additional $400 toward the balance: savings/debt category
That gives you a clearer picture of your budget.
Should Retirement Contributions Count Toward the 20%?
Retirement contributions generally belong in your savings category.
But remember the take-home pay issue.
If retirement contributions are already deducted before your paycheck reaches your account, decide whether you are calculating your savings rate before or after that deduction.
Consistency matters more than choosing one perfect method.
Should Employer Contributions Count?
You can track employer contributions separately.
If you want to know the total amount going toward retirement, employer contributions are relevant.
If you want to know how much of your personal income you are choosing to save, looking at your own contributions separately can be clearer.
50/30/20 vs. Zero-Based Budgeting
The 50/30/20 rule is broad.
Zero-based budgeting is detailed.
With zero-based budgeting, every dollar is assigned a purpose.
For example:
Income: $5,000
Planned spending, debt payments, and savings: $5,000
Unassigned money: $0
The zero does not mean you spend everything.
Savings also receives an assignment.
Zero-based budgeting may work well if you frequently overspend and want tight control.
50/30/20 may work better if you want simplicity.
50/30/20 vs. Pay Yourself First
The pay-yourself-first approach starts with saving.
Suppose you bring home $5,000 per month.
You automatically transfer $1,000 to savings and investments.
Then you manage your lifestyle using the remaining $4,000.
For people who already control their spending well, this can be simpler than tracking fixed percentages for needs and wants.
How to Build Your Own Budget Ratio
If you want a more detailed step-by-step budgeting system, read our guide on How to Create a Monthly Budget That Actually Works.
You do not have to choose between only 50/30/20 and 60/20/20.
You can create your own ratio.
Start with:
Step 1: Calculate your monthly take-home income
Suppose it is:
$5,500
Step 2: Calculate actual essential expenses
Suppose they total:
$3,025
That is:
55%
Step 3: Choose a realistic savings target
Suppose you want to save:
$1,100
That is:
20%
Step 4: Calculate what remains for wants
$5,500 − $3,025 − $1,100 =
$1,375
That is:
25%
Your custom budget becomes:
55% needs
25% wants
20% savings
That may fit your life much better than forcing 50/30/20.
A Simple 50/30/20 Calculator
If you want to test the original framework, use:
Needs = monthly take-home pay × 0.50
Wants = monthly take-home pay × 0.30
Savings = monthly take-home pay × 0.20
Example with $6,500 monthly take-home pay:
Needs:
$6,500 × 0.50 = $3,250
Wants:
$6,500 × 0.30 = $1,950
Savings:
$6,500 × 0.20 = $1,300
Then compare these targets with your actual spending.
When the 50/30/20 Rule Works Best
The method can work especially well if:
- Your income is stable
- Your essential expenses are manageable
- You are new to budgeting
- You dislike complicated spreadsheets
- You want a simple monthly framework
- You need help balancing spending and saving
The simplicity itself is an advantage.
A budget you actually follow is more useful than a sophisticated system you abandon.
When Another Method May Be Better
Consider a different system if:
- Your income changes significantly every month
- Necessities consume most of your income
- You are aggressively paying down debt
- You want to maximize savings
- You regularly overspend despite using broad categories
- You need detailed control over every dollar
In those situations, zero-based budgeting, pay-yourself-first, or a custom percentage system may be more useful.
Should You Still Use the Rule in 2026?
The key is to stop thinking of 50/30/20 as a pass-or-fail test.
If your budget is 52/28/20, you have not failed.
If it is 60/25/15, you have not failed.
If you are saving 30% and only spending 15% on wants, you do not need to increase discretionary spending simply to reach the traditional percentages.
The real questions are:
Can you afford your essential expenses?
Are you avoiding unsustainable debt?
Are you making consistent progress toward savings goals?
Can you maintain the budget over time?
Those questions matter more than perfect percentages.
Frequently Asked Questions
Is the 50/30/20 rule still good in 2026?
It can still be a useful starting framework, especially for beginners. However, higher essential expenses may make the traditional percentages unrealistic for some households.
Is the 50/30/20 rule based on gross or net income?
The rule is commonly applied to monthly net or take-home income. CFPB budgeting materials use net income when explaining the framework. Tüketici Finansmanı Dosyaları
What if my needs are more than 50%?
Calculate why they are high before making changes. You may need to temporarily use a custom ratio such as 60/20/20 or another allocation that better reflects your situation.
Is saving 20% enough?
It depends on your goals, retirement plans, debt, age, income, and other financial obligations. Twenty percent is a useful benchmark, not a universal requirement.
Is it okay to save more than 20%?
Yes. The 20% category is not a maximum. If you can save or invest more while comfortably covering your needs, you can choose a higher savings rate.
What is better than the 50/30/20 rule?
There is no single budgeting method that is best for everyone. Zero-based budgeting offers more detail, while pay-yourself-first can work well for people who want to prioritize saving.
Can I use 60/20/20 instead?
Yes. A custom ratio can be more practical if your necessities exceed 50% of take-home income.
The Bottom Line
The 50/30/20 budget rule still has value in 2026.
Its biggest strength is simplicity.
It gives you a quick way to compare how much money is going toward necessities, lifestyle spending, and your financial future.
But it should not be treated as a financial law.
The CFPB itself notes that not everyone can follow a standard rule of thumb and that people may need a personal spending guideline that fits their circumstances. Tüketici Finansmanı Dosyaları
Start with 50/30/20.
Compare it with your actual spending.
Then adjust.
Your final budget might be 55/25/20, 60/20/20, 70/20/10, or something completely different.
What matters most is that your budget is realistic, sustainable, and helps you consistently make financial progress.
Disclaimer: This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax, or legal advice.